What is Casca?
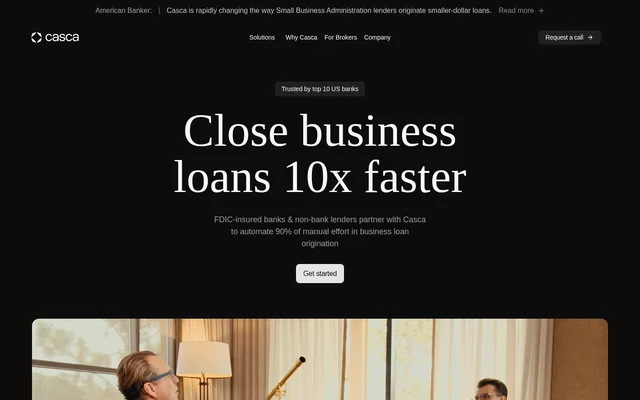
Casca is an AI-powered loan origination tool for banks and non-bank lenders handling business loans. Casca brings digital applications, applicant communication, financial document analysis and approval workflows into the lending process. The website identifies FDIC-insured community banks, regional banks and nationally leading lenders as customers for its lending automation.
Casca focuses on reducing manual work across small business lending rather than providing only a document-reading tool. The website describes Huntington and Live Oak integrating Casca’s generative AI tools to speed up small business lending and reduce costs for SBA 7(a) loans. Celtic bank is also named as choosing Casca for SBA 7(a) loan origination.
What Casca can do
Casca supports tasks from initial application through document preparation. Casca combines applicant-facing functions, such as a digital application and loan assistant, with lender-facing functions for verification, financial analysis and approvals. The website lists 30+ native integrations with data providers and document analysis covering 100+ document types.
- Casca pre-fills applicant information in digital loan applications.
- Casca answers applicant questions and automates follow-ups through an AI loan assistant.
- Casca analyzes 40+ business verification checks.
- Casca integrates with credit bureaus for credit checks.
- Casca analyzes tax returns, bank statements, financial statements and rent rolls.
- Casca calculates financial ratios and supports automated decisions.
- Casca tracks loan progress through a portal.
- Casca generates documents through integrated document preparation.
How Casca works
Casca starts the borrower-facing workflow with a digital application and automatic pre-fill of applicant information. Casca’s AI loan assistant handles questions and follow-ups, while a portal tracks loan progress. The website describes the assistant as available 24/7 and lists a 2-3min response time for follow-up interactions.
Casca supports lender-side processing through native integrations, business verification checks and credit bureau connections. Casca analyzes submitted financial documents, calculates financial ratios and supports digital approvals with automated decisions. Integrated document generation extends the workflow into document preparation. The website provides a demo request as the route for prospective lenders to explore Casca.
Who Casca is for
Casca serves institutions originating business loans, including FDIC-insured community banks, regional banks and non-bank lenders. Casca also addresses underwriting work that involves reading financial documents and transferring figures from PDFs into spreadsheets. The stated use cases center on small business lending, including SBA 7(a) loan origination.
- Casca helps lenders prequalify business loan applicants through digital intake.
- Casca supports underwriters analyzing financial documents and calculating ratios.
- Casca helps lending teams manage applicant follow-ups and track loan progress.
- Casca supports banks modernizing SBA 7(a) loan origination.
Casca strengths and scope
Casca’s documented strength is coverage across connected lending tasks: applications, communication, verification, document analysis, approvals and document generation. Casca combines borrower-facing assistance with tools for underwriting teams, rather than limiting its scope to application collection. The website describes business lending workflows and named banking relationships, with a demo request available for institutions evaluating those capabilities.
Casca FAQ
What is Casca?
Casca is an AI-powered business loan origination tool for banks and non-bank lenders. Casca automates digital applications, applicant communication, verification checks, financial document analysis, loan progress tracking and document preparation.
Who is Casca for?
Casca is for FDIC-insured community banks, regional banks and non-bank lenders handling business loans. Casca also supports underwriting teams that analyze financial documents, with the website specifically describing small business lending and SBA 7(a) loan origination.
What documents can Casca analyze?
Casca analyzes tax returns, bank statements, financial statements and rent rolls, among other financial documents. Casca’s website states support for 100+ document types and describes financial ratio calculations as part of its lending workflow.
Does Casca integrate with data providers and credit bureaus?
Casca offers 30+ native integrations with data providers and an integration with credit bureaus for credit checks. Casca uses these connections alongside business verification, document analysis and digital approval capabilities in loan origination workflows.
Does Casca provide an AI loan assistant?
Casca provides an AI loan assistant for applicant questions and follow-ups. Casca’s website lists 24/7 availability for questions and a 2-3min response time for follow-ups, alongside digital applications and a loan progress portal.
How can lenders get access to Casca?
Casca offers a demo request through its website for lenders exploring its business loan origination capabilities. Casca presents its offering to FDIC-insured banks and non-bank lenders seeking to modernize lending processes.
From the community
No reviews yet
Be the first to review this tool. What you write helps the next person choose.